Build data skills that transfer in the Data Foundations Lab.
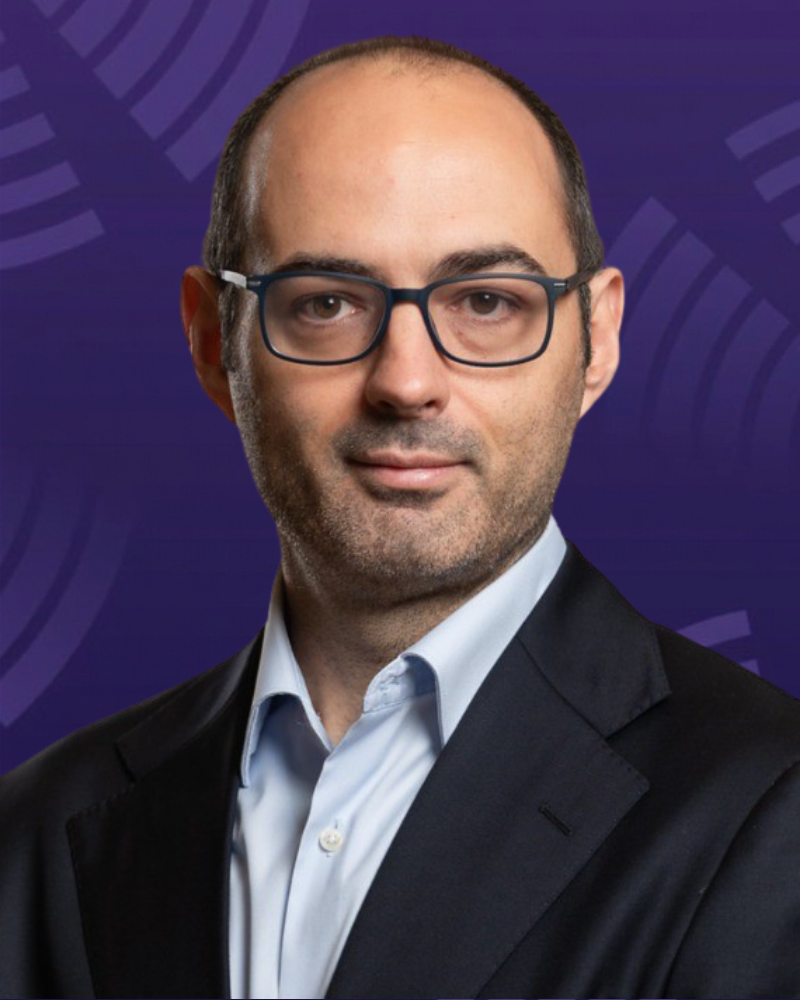
Ivan Blanco, PhD
Image
Country of origin: Spain
Residence: Spain
Other places of work or residence: France, United States, United Kingdom
Languages: Spanish (native), English (fluent)
Bio
Ivan Blanco is associate professor with tenure and Director of the Master in Finance programs at CUNEF Universidad, where he teaches and researches at the intersection of machine learning, deep learning, and empirical asset pricing. He is also the Founder and Director of Noax Capital, a quantitative investment and research firm specializing in systematic equity strategies for institutional and high-net-worth investors. His work bridges academia and industry, combining rigorous financial econometrics with cutting-edge AI techniques to better understand and forecast asset returns. Before founding Noax Capital, he held research and professional roles at Banco Santander, BBVA, and Arfima Trading, gaining hands-on experience in financial modeling and derivatives trading.
Employment
- CUNEF Universidad – Director, Master in Finance – Madrid, Spain – 2024 to present
- CUNEF Universidad – Associate Professor of Finance – Madrid, Spain – 2023 to present
- Noax Capital – Founder & Director – Madrid, Spain – 2024 to present
- WorldQuant University – Instructor – 2016 to present
- Arfima Trading – Quant Portfolio Manager – Madrid, Spain – 2015–2017
- Banco Santander – Quant – Madrid, Spain – 2009-2010
- BBVA – Quant – Madrid, Spain – 2008-2009
Education
- PhD, Finance and Quantitative Methods – University Carlos III – Madrid, Spain – 2016
- MSc, Finance and Quantitative Methods – University Carlos III – Madrid, Spain – 2012
- MBA, EOI & EM - Lyon Business School – Madrid, Spain, and Lyon, France – 2008
- B.S, M.S Aerospace Engineering – Universidad Politécnica – Madrid, Spain – 2006
Research
- Blanco, Iván; Martín-Flores, José María; Remesal, Alvaro: "Climate shocks, institutional investors, and the information content of stock prices", Journal of Corporate Finance, 86, Art.102567, 2024
- Blanco, Iván; De Jesus, Miguel; Remesal, Alvaro: "Overlapping momentum portfolios", Journal of Empirical Finance, 72, 1-22, 2023
- Blanco, Iván; García, Sergio: "Options Trading and The Cost of Debt", Journal of Corporate Finance, 69, 102005, 2021
- Blanco, Ivan; Peña, Ignacio; Rodríguez, Rosa: "Modelling Electricity Swaps with Stochastic Forward Premium Models", The Energy Journal, 39 (2), 2018
- Baldominos, Alejandro; Blanco, Iván; Moreno, Antonio; Iturrarte, Rubén; Bernardez, Oscar; Afonso, Carlos: "Identifying Real Estate Opportunities using Machine Learning", Applied Sciences, 8 (11), Art. 2321, 2018
- Blanco, Iván; Wehrheim, David: "The Bright Side of Financial Derivatives: Options Trading and Firm Innovation", Journal of Financial Economics, 125 (1), 99-119, 2017
- Balbás, A., Blanco, I. and Garrido. J, "Measuring risk when expected losses are unbounded". Risks. 2014; 2(4):411-424
WQU Programs
- Master of Science in Financial Engineering
Fun Fact
Before pursuing a career in finance, Ivan played football at a competitive level. He was part of the junior teams of Real Madrid, Atlético de Madrid, and Getafe until he was 18 years old.